Private equity-backed operators are expanding through acquisitions, with processing capacity, customer relationships and succession planning influencing the next phase of consolidation in electronics recycling and ITAD.
Merger and acquisition activity in the US ITAD industry has held steady over the past two years, although the reasons companies are buying have evolved. Acquisitions are increasingly being used to expand processing capacity, enter new markets and obtain capabilities that would take longer to develop internally.
Compliance Standards identified 22 core ITAD transactions between October 2024 and July 2026, followed by another announced transaction involving Iron Mountain and ViaTeK. Eight deals were recorded during the first eight months of 2025, matching the number during the comparable period in 2026.
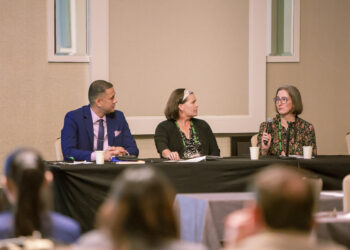
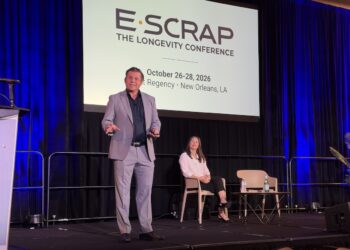
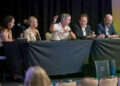
I presented the findings during an industry investment panel at the E-Scrap Conference 2026 featuring Aaron Zeper, CEO of DMD Systems Recovery; Bill Vasquez, CEO of Paladin EnviroTech; and Addison Helm, vice president at SER Capital Partners.
While the transaction count has remained stable, the buyer population is expanding. Alongside private equity-backed acquisition programs, Asian industrial groups are investing in US recycling businesses, often with an interest in securing recovered materials and strengthening downstream supply chains.
Buying rather than building
DMD Systems Recovery, which received a majority investment from Tailwind Capital in September 2025, expects to need additional processing capacity in 2027. Acquisitions offer one way to meet that demand without the lengthy process of opening and certifying new facilities.
“From the time it takes to find a site, get a site up and running, get certified, et cetera, it takes too long,” Zeper told the audience.
DMD is interested in businesses with available processing space, particularly in markets in which it wants to expand. However, Zeper said acquisition candidates must also fit the company’s service-oriented business model. Charging customers for services is a fundamental requirement.
The company acquired another business in 2024 and added Lifespan Technology in June 2026. Zeper said DMD had four potential acquisitions under letters of intent as of the time of the panel earlier this week.
Paladin EnviroTech has taken a somewhat different approach, combining acquisitions of operating companies with asset purchases and new facility development.
Vasquez said the company had evaluated about 50 businesses over the preceding year and completed five acquisitions. Its expansion into the Netherlands and Ireland supports international customer relationships, while the purchase of assets in Phoenix added capacity without an accompanying customer base.
Paladin has also developed a Dallas operation designed to process wind turbines, extending its activities beyond traditional electronics recycling.
For both companies, the decision to acquire depends on the needs of the existing business. A facility can be attractive because of its location or available space, even when its customer base is relatively small.
Continuity amid fragmentation
The US certified processing network remains heavily fragmented. Compliance Standards identified 843 facilities certified under R2 or e-Stewards, operated by about 650 companies. Single-site operators account for 87% of those companies and control about 67% of the facilities.
At the other end of the market, about 2% of companies operate five or more sites, collectively accounting for 12% of certified facilities.
The figures illustrate the extent of the industry’s small-business ownership. They also raise questions about how operators will finance the investments increasingly required by enterprise customers.
Small companies can remain competitive, particularly when they specialize in services for which customers are willing to pay a premium. However, smaller operators face growing costs associated with compliance, information security and technology integration.
Zeper said enterprise customers increasingly expect ITAD providers to connect with internal systems, including ServiceNow and other platforms used to manage technology assets. Supporting these integrations requires technical expertise that can be expensive for a small operator to maintain.
Ownership succession adds another consideration. Many electronics recycling and ITAD businesses were established around the turn of the century, and their founders are approaching retirement.
For buyers, the ability of a company to continue operating after its founder leaves is a significant part of the acquisition assessment.
Preparing a business for sale
Helm advised owners considering a sale over the next several years to begin with their financial records. “Number one is fix the books,” he said.
He said businesses where personal expenses were mixed with company accounts or inventory records were difficult to reconcile. Such problems complicate due diligence and can reduce the value a buyer will pay.
Customer relationships present another risk, particularly when the owner remains the principal salesperson and maintains direct control over major accounts.
Helm encouraged owners to transfer responsibilities gradually to capable managers so prospective buyers can have confidence in customer retention.
Vasquez agreed, explaining that Paladin looks closely at the management team beneath the owner. Businesses with experienced second-in-command executives are often easier to integrate because day-to-day operations can continue after the sale.
Zeper added that owners should first establish what they want from a transaction. Some are seeking retirement, while others want to remain involved in a larger organization. Those expectations influence which buyer is appropriate and how a transaction is structured.
Favoring recurring services
The panel also addressed the valuation gap between service-oriented ITAD providers and traditional recycling businesses.
Helm indicated that ITAD companies with recurring service revenue can attract valuations around 10 to 12 times EBITDA. Recycling businesses generally trade at lower multiples, often around five to eight times EBITDA.
Investors place a premium on revenue visibility and business models that require less capital investment. However, Helm and Zeper cautioned that company size and earnings consistency can substantially influence the multiplier.
Recent increases in the value of recovered components have complicated valuations, particularly for businesses benefiting from strong prices for memory and other data center equipment.
Zeper said buyers are examining historical earnings and adjusting for unusually favorable market conditions. Companies whose recent profitability depends heavily on elevated component prices should not assume those earnings will receive the same valuation as recurring service revenue.
Data centers attract interest
Data center equipment recovery is influencing expansion plans, although operators are approaching the opportunity from different positions.
Vasquez said Paladin’s European expansion has helped the company serve global accounts, including customers requiring data center equipment recovery. The company is also developing recovery capabilities for materials contained in shredded hard drives.
DMD has traditionally focused on enterprise-wide ITAD contracts covering end-user equipment and data center assets.
Zeper reported strong growth in DMD’s data center business during 2026, while end-user computing volumes from existing customers were weaker. The company seeks additional enterprise contracts and is evaluating acquisitions that could provide greater access to hyperscale data center customers.
He acknowledged that DMD has not established a strong position in that segment and sees acquiring an experienced operator as a possible solution.
Helm said electronics recycling offers investors exposure to data center growth at valuations generally below those associated with data center construction and infrastructure.
He nevertheless cautioned against relying on a single equipment or commodity cycle. Buyers need to consider whether recent earnings can be sustained when market conditions change.
Integration determines the outcome
Acquiring a business is only the beginning of the expansion process. Both operating executives emphasized the difficulties of bringing independently managed companies into larger organizations.
Zeper identified cultural integration as one of the hardest challenges. Acquired companies arrive with established practices and employees accustomed to different ways of working. Those differences require attention even when the businesses appear strategically compatible.
Vasquez said Paladin has tried to avoid integration problems by selecting companies carefully and retaining capable managers. Its approach includes aligning operational systems and providing acquired businesses with resources they previously had to manage independently.
Helm emphasized the value of relationships developed before an acquisition. Familiarity with a company’s management and operating history can improve confidence during due diligence and accelerate negotiations.
The panelists expect consolidation to continue, although none suggested that independent operators would disappear. Specialized businesses can remain viable, and large enterprise customers sometimes prefer maintaining relationships with several providers.
The question for the industry is how much of the existing processing network can meet future requirements without substantial additional investment.
With 843 certified facilities and a predominantly single-site ownership structure, there is considerable room for ownership changes. Acquisitions can help operators expand more quickly, but the longer-term results will depend on the quality of the businesses acquired and how effectively they are integrated.