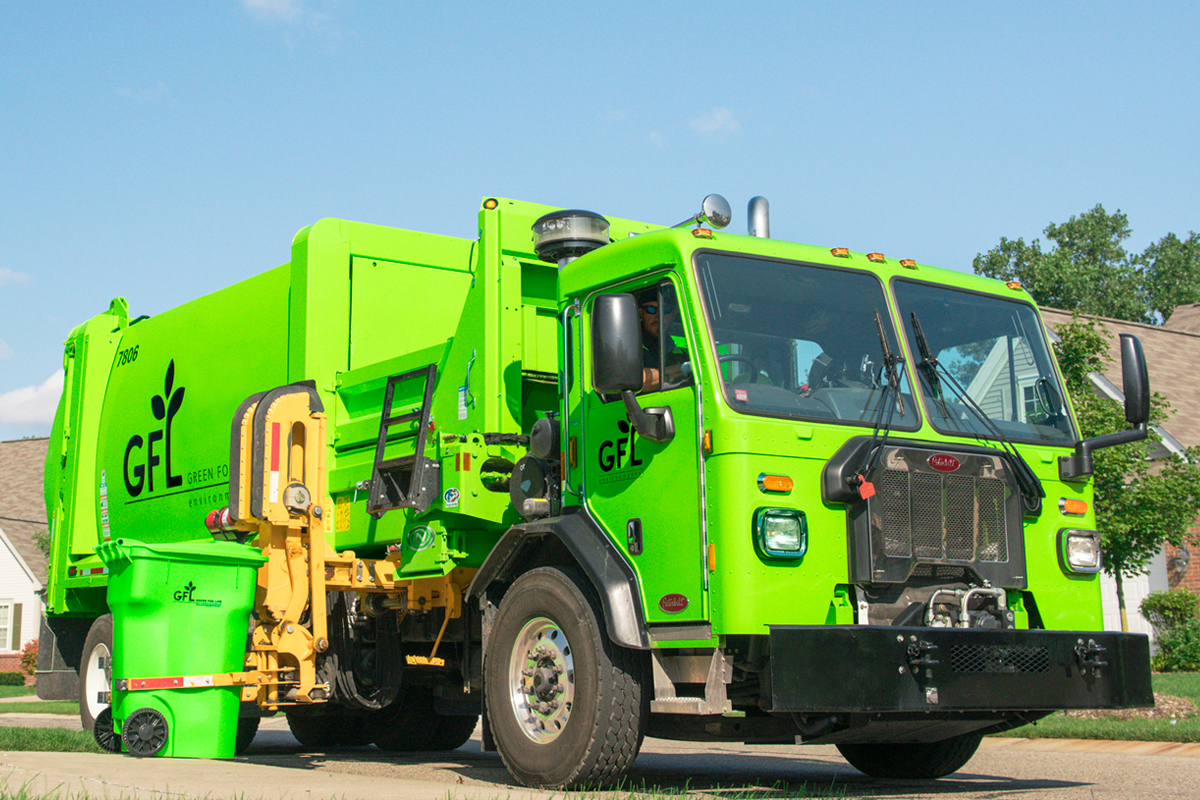
GFL Environmental expects changes to Canadian recycling contracts to weigh on reported growth through year-end and into 2027, even as stronger commodity prices offer support.
“Our volume outlook remains cautious,” CFO Luke Pelosi said during the company’s Oct. 29 third-quarter earnings call, referring to GFL’s broader operations.
The Miami Beach, Florida-based company’s recycling commentary centered on contract structure and extended producer responsibility (EPR) transitions.
At the beginning of the third quarter, GFL restructured a recycling contract in Western Canada, ending its role arranging third-party transportation on a pass-through basis. The change removed CA$13 million (US $9.3 million) in quarterly revenue.
“The profitability of that was de minimis,” Pelosi said. “GFL continues providing recycling services under the contract, and the same revenue effect will carry into the fourth quarter.”
The change reflects lost transportation brokerage revenue. The company did not disclose a corresponding change in recycling tonnage. The companywide volume contribution to revenue growth was nearly flat in the quarter and would have been positive without that contract revision.
GFL expects fourth-quarter volume comparisons to weaken as it laps Canadian EPR transition contracts and exits certain ancillary services in the Midwest. Underlying volumes across the business are expected to remain flat to modestly lower.
EPR transitions are also complicating the comparison for service pricing. Pelosi said the transition has provided a meaningful boost this year, creating a tougher comparison when GFL reaches the same periods in 2027.
“This year we’re getting meaningful support at the price line from some of this EPR-related transition,” he said.
That means the company’s headline pricing growth could slow even as its underlying pricing strategy continues. Management expects to keep raising service prices above internal cost inflation and sees additional opportunities to bring charges closer to those of competitors.
Pelosi estimated EPR benefits would lift this year’s reported service-pricing growth into the low 6% range. Excluding those benefits, growth would be in the low-to-mid 5% range, illustrating why a slower headline figure next year would not necessarily signal weaker pricing execution.
Those service-price increases are separate from the prices GFL receives for recovered commodities.
Commodity pricing added 0.3 percentage points to third-quarter organic revenue growth, although it remained a drag for the first nine months combined. Stronger commodity prices also helped profitability, Pelosi said, providing some relief from higher fuel costs.
GFL’s updated full-year outlook assumes current commodity and diesel prices continue.
Diesel remains a concern for collection and transportation costs. Average diesel prices were more than 60% higher than a year earlier, with another sharp increase in September. Fuel surcharges are recovering much of the increase, but higher costs are also arriving through outside transportation providers and spare parts.
Patrick Dovigi, GFL’s founder and CEO, noted that those indirect costs could require additional service-price increases in 2027 beyond what management anticipated several months ago. Recovery can lag because of contract terms and the timing of fuel-price changes.
Pelosi said GFL expects to refine its surcharge programs to provide better protection. A reversal in diesel prices would help margins, he added.
The company reported third-quarter revenue of CA$2.16 billion, up 27.2% year over year, and raised its annual guidance again. Acquisitions, including SECURE Waste Infrastructure, contributed heavily to that growth.
Dovigi said management remains focused on operational improvements while an independent board committee reviews proposals to take GFL private. Updated proposals are due Nov. 9; no transaction has been announced.
Dovigi said private ownership could give management more flexibility to accelerate capital spending and acquisitions. Either way, he said, the company plans to keep executing its existing operating strategy.
The review has also identified opportunities to improve contract management. Dovigi described using AI tools to examine customer agreements, determine which charges they permit and help employees administer them more consistently.
Dovigi said spending on remaining EPR-related growth projects is winding down. Management is still reviewing investment opportunities and expects to give investors a clearer picture of its capital allocation plans when it releases next year’s outlook.
Management expects to provide detailed 2027 guidance in February. Until then, its recycling outlook rests on navigating contract comparisons, sustaining commodity gains and recovering operating costs.
Dovigi said GFL would adjust its pricing to match changes in inflation.
“If inflation goes up, we will price accordingly, and we will do so in a disciplined fashion,” he said.