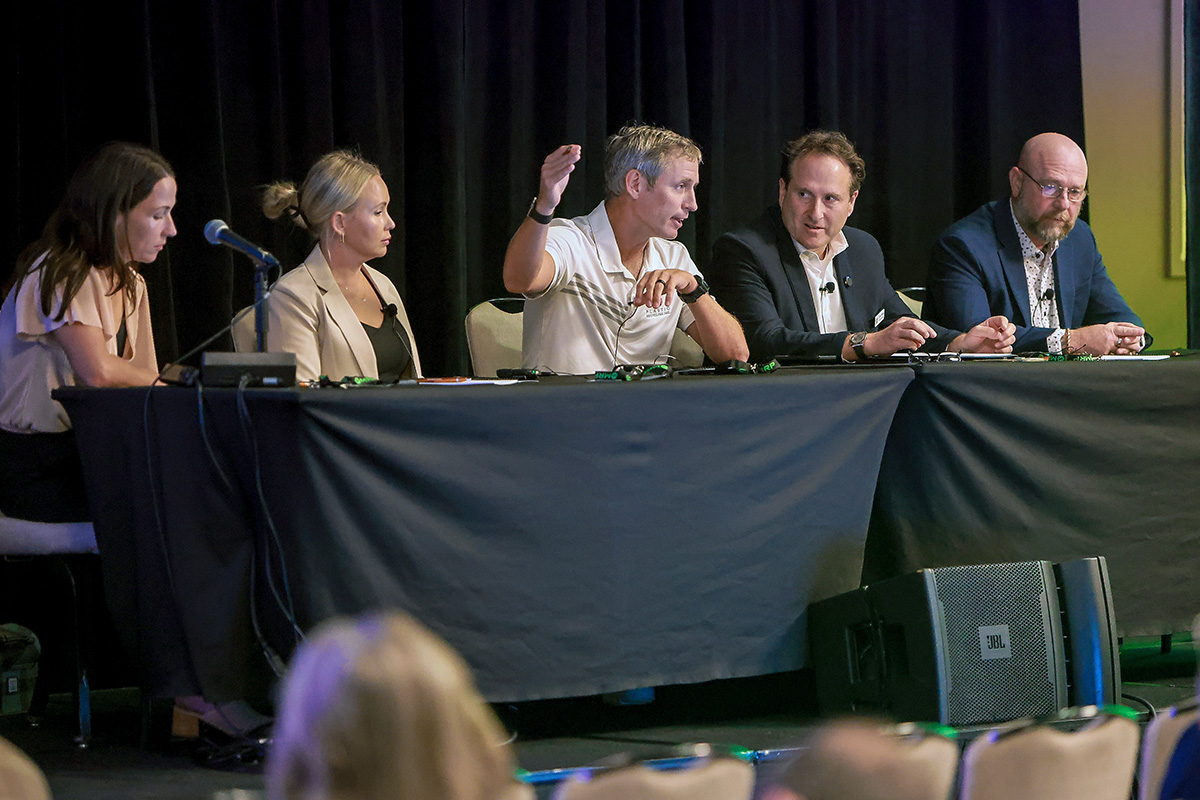
Like common packaging plastics, polymers recovered from end-of-life electronics face weak demand, panelists said during the E-Scrap Conference this week in New Orleans.
But PET, HDPE and PP have dedicated industry groups advocating on their behalf, while high-impact polystyrene (HIPS) and acrylonitrile-butadiene-styrene (ABS) don’t – yet.
During the panel, stakeholders proposed forming a working group to look at creating a voluntary producer responsibility organization (PRO) for e-plastics that involves OEMs, to help fund the sector and make it economically viable.
The US already has some processing capacity for the engineered resins common to electronic devices. But available capacity doesn’t indicate a financially viable system, the panelists said.
E-plastic feedstock loads often have inconsistent yields and incur high fixed processing costs, in addition to the headwinds presented by low virgin-resin prices and weak demand.
The cost of quality resin
For e-plastics, creating the high-quality resin end users require – and complying with the Basel Convention – comes down to separation methods.
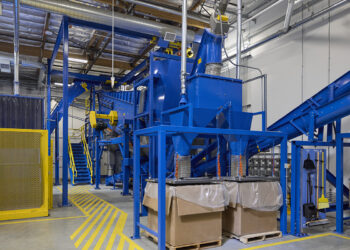
Producing usable, consistent recycled e-plastics requires multiple specialized steps, including the initial sink-float separation, and later electrostatic separation to separate fractions including ABS and PS.
By definition, “mixed plastic” hasn’t gone through electrostatic separation, and shipping it overseas requires the Basel prior informed consent process.
And those processes don’t come cheap.
Brandon Shaw, president of Plastic Recycling Inc. (PRI), said his company has invested $20 million in equipment to process and compound e-plastics, creating “probably one of the best labs in the US.”
PRI entered the e-plastics world about seven years ago – “kind of got into it by accident, and took it as a vertical integration play to take a product that really nobody else wanted or knew what to do with it domestically.” Shaw said the company is now one of the largest PS and ABS compounders in the US, with approximately 200 million pounds of annual capacity.
Still, Clive Hess, president of Houston-based ITAD firm CompuCycle, said most recovered e-plastics are exported rather than being processed domestically, because of unworkable economics. “We can’t compete with the overseas markets.”
Hess added that converters don’t seem to want e-plastics either. “ABS and PS are not friends, and that mix is a mix that most people don’t want. We have people taking samples from us all the time, and they’re very happy to get the samples, and we never ever hear back from them.”
PRI’s Shaw pointed out that mixed ABS/PS plastics require certain compounding equipment and additives to be usable. “We want plastics, but we want economical plastics – that’s the difference.”
Shaw added that his company’s vertical integration and product mix helps hedge the business during volatility and downturns. Even so, e-plastics are among the most difficult streams PRI handles, he said.
Products, partnerships, policy
In addition to the potential voluntary PRO for e-plastics, the panelists offered up several other ways to boost the industry.
Panelist Megan Tabb, commercial director at Synergy Recycling/RePolyTex in North Carolina, said her company has created demand with its Mamba Board, made out of mixed plastic from Synergy’s shredder.
She noted that demand improved when the company moved from a general-purpose board to application-specific products, such as Mamba Suede for structural uses in boat building. The original board wasn’t compatible with some boatbuilding resins, so the company changed its process, and the new product is gaining interest and adoption in the marine industry, Tabb said.
Another way to increase downstream demand and spur investment is to partner with other industries, with automotive OEMs holding the most potential, Shaw said. “If you could leverage those two sectors together, you’ve got a chance.”
The panelists also suggested policy remedies to incentivize recovery and help recycled material compete with virgin plastic. Whether the solution is extended producer responsibility (EPR) fees or recycled-content mandates, “something’s got to stick” to create demand, Shaw said.
“If there’s some way to make this equivalent or on par with virgin, then we’ve got a chance,” he said. “Because, to be honest, I don’t see any silver bullet for plastic recovery from a price perspective anytime soon.”
Ken Thomas, president of Universal Recycling Technologies (URT) in Wisconsin, said “We’ve got all this plastic, and who should pay?”
Even if manufacturers are held responsible, ultimately consumers pay by way of higher prices for products. “I don’t know that I have the answer,” he said, adding: “Right now, it’s the processors, for the record.”
Thomas said the most impactful policy would be mandated recycled content, though he acknowledged it would be “a longer term play.” To provide benefits in the shorter term – the next three to five years – emerging state-level EPR programs and other regulations should define what actually counts as recycling.
Policymakers “have to insist on knowing where that plastic’s going, verifying it all the way down to downstream, and as far as I’m concerned, which compounder it’s going to,” he said. “Because until it’s going to a compounder, it’s not recycled. I mean, it’s that simple.”