Editor’s note: Critical minerals will be featured in sessions at the 2026 E-Scrap: The Longevity Conference Oct. 26-28 in New Orleans.
Rare-earth recycling economics depend on the material being recovered, where it is located, how consistently it can be collected and how much labor is required before chemical processing begins. It does not become commercially viable at a single price or on a single date.
A 2025 study published in the peer-reviewed Journal of Material Cycles and Waste Management found that recycling could reduce costs by as much as 40% compared with primary extraction. Researchers evaluate projects through a series of factors that include capital and operating expenditures, net present value, internal rate of return, break-even prices and cost per kilogram recovered. Those calculations can produce attractive results, but only when the assumptions about feedstock volume, recovery yield and selling prices hold.
The US International Trade Commission identifies a similar set of dependencies: the availability of electronic waste, domestic processing capacity and whether secondary production can compete with minerals from primary sources. For rare earth elements recovered from e-waste, primary material generally remains cheaper. Collection infrastructure remains limited, while small electronic products are difficult to separate at scale.
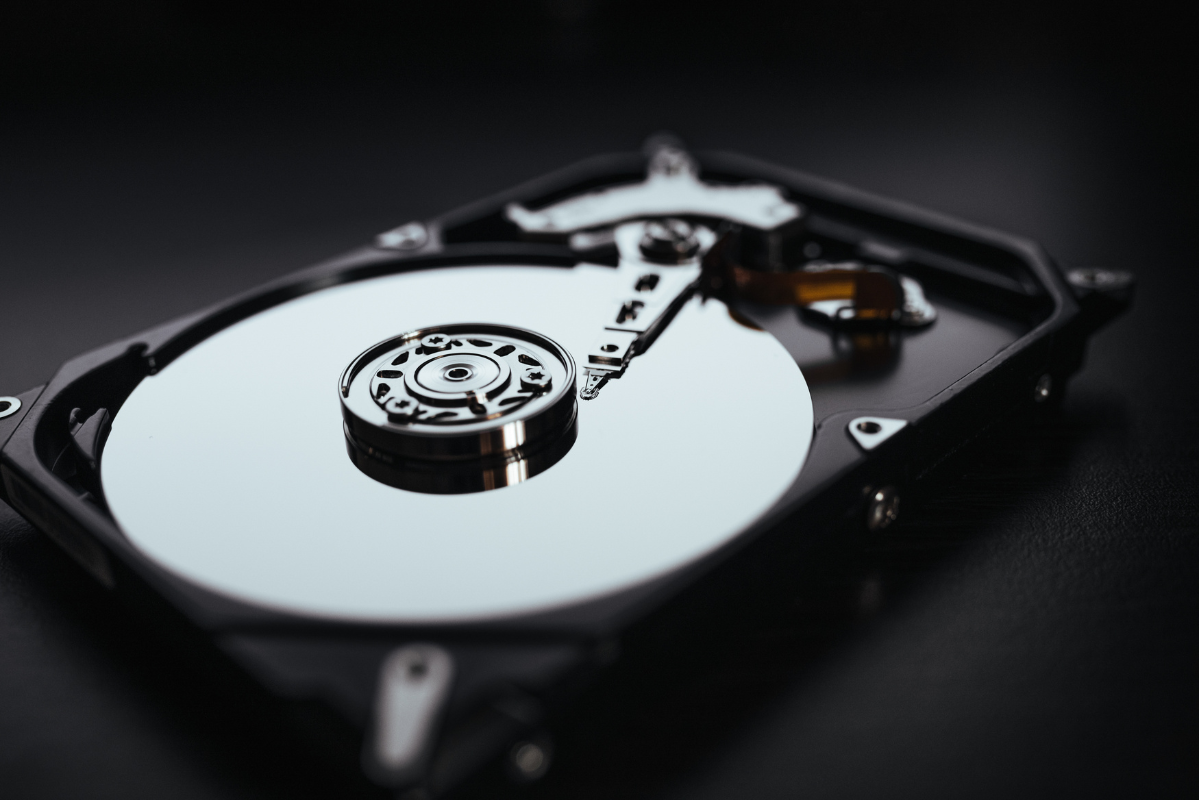
The central obstacle is often collection and disassembly rather than recovery chemistry. Rare-earth-bearing components are small, embedded inside larger products and dispersed across millions of locations. Removing a small magnet from a hard drive can require manual labor worth considerably more than the recovered material. In many consumer devices, the rare-earth content itself is worth only pennies or a few dollars.
Price volatility makes the calculation less predictable. Investments justified during the 2011 rare-earth price spike became far less attractive after prices fell. A process can therefore work technically while its economics deteriorate if feedstock costs rise or recovered-material prices fall.
The economics can improve with larger magnets and organized collection systems. Electric-vehicle motors and wind-turbine generators are important sources of neodymium-iron-boron magnets, and their end-of-life material is concentrated in much larger equipment than most consumer electronics. Vehicles pass through dismantling systems, while wind turbines are generally retired through planned decommissioning. These pathways can provide more identifiable owners, predictable removal points and larger quantities of magnet material per transaction.
Manufacturing scrap is even more attractive because it is concentrated, relatively consistent and available before products enter the consumer market. A techno-economic study involving researchers associated with the Department of Energy’s Critical Materials Institute and Ames Laboratory modeled recycling of neodymium-iron-boron magnet swarf. Depending on the selected process, it projected net profit margins ranging from 12% to 43%. The process studied recovered approximately 97% of the rare-earth elements as mixed rare-earth oxides with purity above 99.5%. While these are modeled results, they show what becomes possible when collection and disassembly have largely been solved.
Other unconventional feedstocks may also work under favorable conditions. A 2025 techno-economic assessment of rare-earth recovery from coal refuse modeled a $35 million initial capital investment, a $262.4 million net present value and a 42% rate of return on investment. Such results depend heavily on process yield, scale, product prices and the composition of the refuse. They establish potential rather than proof that every coal-waste deposit can support a profitable plant.
Government policy is attempting to move more feedstocks across the commercial threshold. In June 2026, the Department of Energy announced $134 million for two demonstration projects designed to establish the commercial viability of recovering and refining rare earths from unconventional feedstocks, including mine tailings, electronic waste and other waste materials. The projects were selected for award negotiations, which DOE explicitly noted did not constitute a commitment to provide funding.
Europe is applying pressure from the demand side. The European Union’s Critical Raw Materials Act establishes 2030 benchmarks under which EU capacity should reach at least 10% of annual strategic-raw-material consumption through extraction, 40% through processing and 25% through recycling. The legislation also seeks to limit dependence on any single third country to no more than 65% of annual consumption of each strategic raw material at any relevant stage of processing.
Collectively, these examples show that commercial viability is emerging source by source. Magnet-production scrap can already support attractive modeled margins, while larger motors potentially improve collection economics because they concentrate more magnet material in fewer units. Dispersed consumer electronics remain more difficult economically unless automation lowers disassembly costs, collection improves or rare-earth prices rise and remain elevated.
DOE funding and European recycling benchmarks are policy bets on advancing that threshold. Governments are choosing to help create commercial conditions now rather than wait for commodity prices alone to make recycling profitable.